French Court Upholds Tax Bill Over €27,340 Private Jet Trip to Morocco
Two executives at a company in Gironde said their trip to Essaouira was intended to protect a real estate investment in Morocco. The tax authorities treated the expense as a taxable personal benefit. Ten years after the flight, a French court has upheld the tax reassessment.
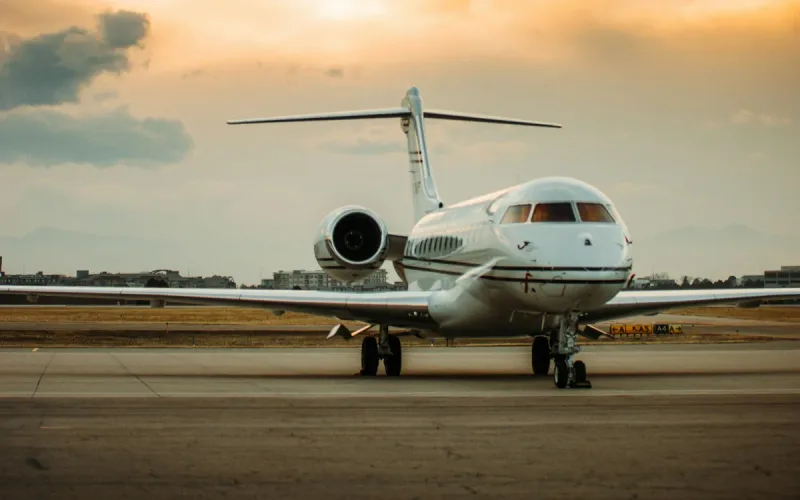
On 26 March 2016, a couple who ran a company left Bordeaux aboard an air taxi for Essaouira. They returned on 10 April. The round trip cost €27,340, paid by their company, ADF, based in Saint-Loubès, in Gironde.
The two co-managers said the trip had a business purpose. Their company owned a subsidiary in Morocco, ADF Maroc, which had acquired a villa in Essaouira with financing from its parent company.
The male executive, who was also president of the board of a co-ownership on the Essaouira golf course, said he had taken part in negotiations over the Essaouira-Mogador tourism project. The couple said the aim was to protect the value of the investment amid a real estate slowdown. His wife is said to have accompanied him to support him because of his health.
But during a tax audit, the authorities refused to treat the bill as a business expense. They deemed the €27,340 a benefit granted to the executives and demanded €20,928 in income tax, social contributions and penalties.
In a ruling issued on 21 October 2026, the Bordeaux Administrative Court of Appeal upheld the reassessment. Economic press articles, a letter from France’s honorary consul in Essaouira and a property valuation submitted by the couple did not prove that the trip was directly related to the company’s business.
Essaouira villa at the center of a second tax reassessment
The same day, the judges also ruled on the company’s own appeal. In a second ruling, they upheld the refusal to deduct the €27,340 air travel costs from its taxable profit.
Another amount was disputed: €200,000. The company had booked this provision to cover a potential loss on a €615,479 receivable from its Moroccan subsidiary, linked to the financing of the villa. The judges found that the evidence presented did not justify either the risk of loss or the amount set aside.
In upholding the 40% penalty applied to both adjustments for deliberate failure to comply, the court also pointed to a revealing pattern: the executives had acknowledged that they normally paid for their own trips to Morocco.
The company had obtained a €138,059 tax rebate in December 2024 on another issue arising from the audit. However, the judges upheld the reassessments relating to the air travel costs and the provision linked to Essaouira.